In plain words
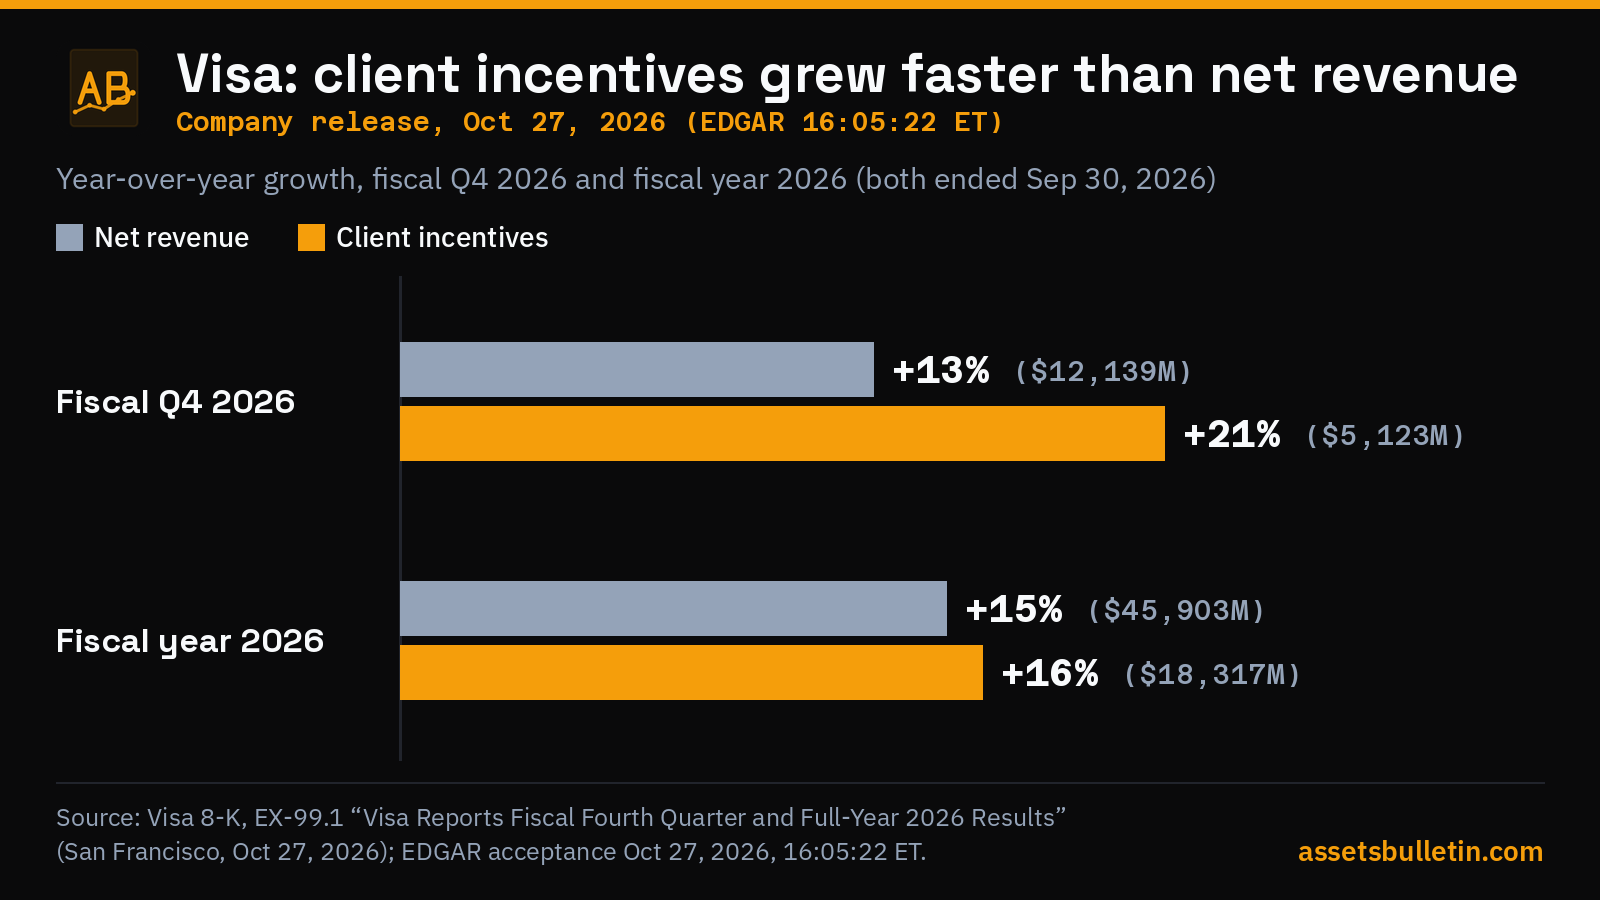
Visa earns a small fee each time someone pays with one of its cards. In the year to September, it took in a record $45.9 billion, up 15%. In the last quarter alone, revenue rose 13%, to $12.1 billion. But it also pays banks and merchants to keep issuing and accepting its cards. Those "client incentives" grew faster than revenue, at 21%. For the coming year, management expects growth to slow to the "low double digits". A quarter of Visa's volume comes up for contract renewal, so it expects to pay out more incentives.
The finding
The Editor's view: Visa's machine is intact, but fiscal 2027 is a year of paying to keep it. Payments volume and cross-border spending are still growing. What changes is the cost of loyalty. Renewals rise to about 25% of volume, from about 20%. Incentives are already outrunning revenue. And the guide steps down from 15% revenue growth to low double digits. The result, in the Editor's view, is a slower year by design, not a demand problem.
For educational purposes only; not investment advice.